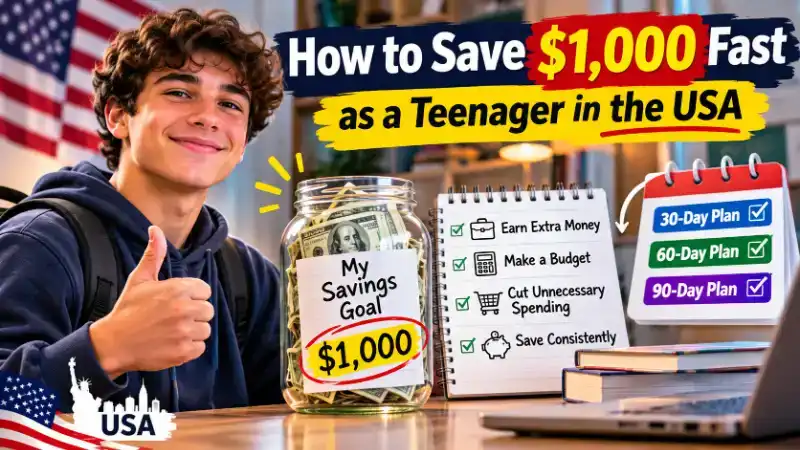
Saving your first $1,000 as a teenager can feel impossible, especially when you don’t have a regular job. Maybe you only get a small allowance, earn money from occasional chores, or work a few hours after school.
You want to save money, but somehow it disappears before you make much progress.
The good news? You don’t need a full-time job to start building savings. You need a clear target, a realistic way to bring in money, and a plan that stops you from spending everything you earn.
If you’re wondering how to save $1,000 fast as a teenager in the USA, this guide will help you figure out what works for your age, income, and schedule.
You’ll also learn how to build a 30-, 60-, or 90-day savings plan without relying on unrealistic promises.
Quick Answer: To save $1,000 in 30 days, you need to set aside about $33.34 per day. For 60 days, the target drops to $16.67 daily. If you give yourself 90 days, you need about $11.12 per day. Most teenagers can work toward these goals by combining available income, safe earning opportunities, and lower spending. The best timeline depends on how much money you actually have coming in.
| Savings Timeline | Amount to Save Per Day | Total Goal |
|---|---|---|
| 30 days | $33.34 | $1,000 |
| 60 days | $16.67 | $1,000 |
| 90 days | $11.12 | $1,000 |
The daily amounts are rounded up slightly to make sure you reach the target.
FIND YOUR AGE - IN YEARS, MONTHS, DAYS, HOURS & SECONDS!
How Fast Can a Teenager Realistically Save $1,000?
Here’s the first thing you should understand: saving $1,000 quickly is possible for some teenagers, but not everyone has the same opportunity.
A 17-year-old with a part-time job may reach the goal much faster than a 13-year-old who only receives birthday money or occasional allowance.
That doesn’t mean one person is better at saving.
It simply means their financial situations are different.
Before choosing a deadline, look at your current income, available time, and money you already have saved.
Calculate Your Weekly Savings Target
You don’t have to guess how much to save.
Use this simple formula:
Weekly Savings Needed = ($1,000 − Current Savings) ÷ Number of Weeks
For example, suppose you already have $200 saved and want to reach $1,000 in eight weeks.
You still need $800.
Divide $800 by eight weeks, and your target becomes $100 per week.
That’s easier to plan around than starting without knowing your goal.
Here’s what saving $1,000 from zero looks like using different weekly schedules:
| Time Available | Weekly Savings Needed |
|---|---|
| 4 weeks | $250 |
| 8 weeks | $125 |
| 12 weeks | $83.34 |
| 16 weeks | $62.50 |
| 20 weeks | $50 |
| 26 weeks | $38.47 |
Keep in mind that four weeks means 28 days, not exactly 30. The same difference applies when comparing 12 weeks with 90 days.
When Is a 30-Day Goal Too Aggressive?
Saving $250 per week sounds exciting, but ask yourself one question:
Can I actually save that much after my necessary expenses?
If you earn only $50 each week, a $250 weekly target won’t work without additional money.
You might need a longer deadline, occasional extra income, or a combination of both.
School also matters. You shouldn’t sacrifice your classes, sleep, or safety just to finish a savings challenge faster.
For teenagers with limited income, a 90-day plan or even a six-month plan may be more realistic.
The goal is to save $1,000, not to create a money problem while trying to solve one.
Find Out How Much Money You Can Actually Save
One common reason teenagers struggle to save is that they don’t know where their money goes.
You might receive $20 from your parents, make $25 doing a small job, and feel like you have plenty of cash.
Then you buy a few snacks, spend money on a game, and suddenly most of it is gone.
Before looking for new ways to earn, figure out what you can already save.
Add Up Your Allowance, Gifts, and Job Income
Start by writing down every source of money you receive.
This could include:
- Weekly or monthly allowance
- Earnings from a part-time job
- Babysitting or pet-sitting income
- Money from agreed paid chores
- Birthday or holiday gifts
- Money from selling unused belongings
- Other occasional earnings
Separate regular income from one-time payments.
For example, if you earn $40 every week and receive $100 as a birthday gift, don’t treat that birthday gift like something you’ll get every month.
Your regular income helps you plan weekly savings. Extra money can help you reach your goal sooner.
Also, count the money you actually keep after taxes, transportation, supplies, and other work-related costs.
Make a Simple Budget Before You Start
You don’t need a complicated budgeting app.
A notebook or a basic spreadsheet works fine.
Imagine you receive $20 in allowance and earn another $25 from an occasional permitted job each week.
Your weekly budget might look like this:
| Money In and Out | Amount |
|---|---|
| Weekly allowance | $20 |
| Money earned | $25 |
| Total income | $45 |
| Snacks and other optional purchases | -$10 |
| Available for savings | $35 |
If you save $35 every week, you’ll need about 29 weeks to build $1,000 from zero.
That’s not especially fast, but now you understand your starting point.
You can also try a simple budgeting method like the 50/30/20 rule, which separates money into needs, wants, and savings.
However, that rule isn’t perfect for every teenager.
If your family covers most necessary expenses, you might be able to save more than 20% of your income. If you pay for transportation, school supplies, or other essentials, you may need to save less.
Build your budget around your real situation.
Ways to Earn Extra Money as a Teenager in the USA
If your current income isn’t enough to reach $1,000 quickly, earning extra money may help more than cutting every small purchase.
But there’s something important to remember.
Not every job is available to every teenager.
Your age, state laws, school schedule, and the type of work all matter.
Here are some ways to explore extra income based on your age.
Money Ideas for 13-Year-Olds
If you’re 13, getting a regular job at a store or restaurant usually isn’t an option under federal child labor rules.
However, certain casual activities may be possible.
For example, you could talk with your parents about:
- Casual babysitting for a family you already know
- Helping with agreed paid household chores
- Looking after a familiar family’s pet with adult approval
- Helping relatives organize books or belongings
- Doing small, safe tasks that are permitted where you live
Suppose your parents agree to pay you $10 each week for extra chores beyond your usual responsibilities.
That’s $40 over four weeks.
It won’t get you to $1,000 immediately, but it’s a start.
Be careful about assuming every neighborhood job is automatically legal. Federal rules contain exceptions for activities such as casual babysitting, but other types of paid work may be restricted, and state rules can differ.
For younger teens, working with trusted adults is the safest place to begin.
Earning Options for Ages 14 and 15
At 14 or 15, you may have more choices.
Certain retail jobs, cashier duties, shelf stocking, tutoring, and other nonhazardous activities may be permitted under federal rules.
You could also explore casual babysitting, pet sitting, or permitted local services.
For example, imagine you find a legal after-school job that gives you enough hours to save $60 per week after expenses.
Over eight weeks, that adds up to $480.
If you combine that with allowance savings or other money you already have, your $1,000 target becomes much closer.
Still, don’t apply for a job without checking the age requirements.
Federal rules limit both working hours and job duties for 14- and 15-year-olds. Your state may have additional restrictions.
Part-Time and Summer Jobs for Ages 16 and 17
If you’re 16 or 17, you generally have access to a wider range of nonhazardous jobs.
Some possibilities include:
- Retail cashier or store assistant
- Restaurant host or other permitted food-service work
- Seasonal store positions
- Certain camp or recreation support roles
- Tutoring younger students
- Babysitting or pet sitting
- Other approved weekend or summer jobs
Summer break can be a useful time to work toward a savings goal because you may have more free time.
Imagine saving $100 per week from a summer job.
After ten weeks, you would have $1,000.
Of course, the actual amount depends on your pay, hours, taxes, transportation costs, and other expenses.
Even at 16 or 17, some hazardous duties remain prohibited under federal law. State rules can limit work hours and require permits as well.
Choose a job that fits around school and leaves you enough time to rest.
How to Save $1,000 Without a Regular Job
What if you can’t find a job?
You can still start saving, but you may need more time.
Instead of depending on one large source of income, look for several smaller ones.
For example:
| Possible Source | Example Amount |
|---|---|
| Money already saved | $100 |
| Family-approved sale of unused items | $150 |
| Allowance saved over 10 weeks | $200 |
| Occasional permitted work over 10 weeks | $300 |
| Additional gifts or earnings | $250 |
| Total | $1,000 |
These are example amounts, not guaranteed earnings.
The final $250 might never arrive, and some teenagers won’t receive a regular allowance at all.
That’s why it’s better to build your main plan around money you can reasonably expect, then treat unexpected cash as a bonus.
If you have no income and nothing available to sell, you can’t save $1,000 out of nothing. Your first step is to find an appropriate income source or adjust your timeline.
Turn Unused Items Into One-Time Savings
Look around your room.
Do you have old video games, books, clothes, or accessories you no longer use?
If they belong to you and you have permission to sell them, they may be worth something to another person.
For example, you might sell:
- An old game you no longer play
- Clothes that no longer fit
- Books in good condition
- Sports equipment you don’t use
- Accessories you no longer need
Ask a parent or guardian to help with online listings, payments, and meeting buyers.
Some selling platforms require users to be adults, so don’t create accounts using false ages or someone else’s information without permission.
And remember to subtract seller fees or shipping costs from what you expect to save.
One-time sales can help you reach your goal, but they aren’t a replacement for steady income.
Know the US Rules Before Taking a Teen Job or Side Gig
Making money is useful, but earning it safely and legally matters more.
In the United States, the Fair Labor Standards Act (FLSA) sets federal rules for many jobs involving workers under 18.
The U.S. Department of Labor (DOL) provides guidance on which jobs young people may perform.
Check Federal and State Work Restrictions
For most covered nonagricultural jobs, federal rules for 14- and 15-year-olds include these limits:
| Work Situation | Federal Limit |
|---|---|
| School day | Up to 3 hours |
| Week when school is in session | Up to 18 hours |
| Non-school day | Up to 8 hours |
| Week when school is not in session | Up to 40 hours |
| Normal permitted work hours | 7 a.m. to 7 p.m. |
| June 1 through Labor Day | Evening limit extends to 9 p.m. |
These rules have certain exceptions for approved programs and particular types of work.
For 16- and 17-year-olds, federal law generally doesn’t place the same limits on working hours, but it still prohibits certain hazardous occupations.
State laws may set stricter limits or require work permits.
Check the U.S. Department of Labor’s youth employment rules and your state’s requirements before accepting a job.
Understand Basic Taxes on Side-Hustle Earnings
Another thing teenagers sometimes miss is taxes.
If you earn money as an employee, your employer may withhold taxes from your paycheck.
If you’re self-employed, the rules can be different.
The IRS generally requires a federal tax return when you have $400 or more in net earnings from self-employment, even if you’re a teenager.
Net earnings are not always the same as the total money customers pay you.
For example, if you receive $500 for services but have $100 in allowable business expenses, your net profit may be $400.
Whether those expenses qualify depends on the circumstances.
Selling your own used belongings is also not necessarily the same as running a resale business.
Keep records of money earned and expenses, and ask a parent or qualified tax professional for help if needed.
You can read the IRS guidance on gig-work taxes for more information.
Avoid Jobs That Ask You to Pay First
Be careful when someone promises easy money online.
A message might say you can earn hundreds of dollars by clicking buttons, rating products, or completing simple tasks.
Then the person asks you to pay a fee or deposit money to receive your earnings.
That’s a major warning sign.
The Federal Trade Commission (FTC) warns about fake job offers and online task scams.
Never send money just to get paid for a job. Avoid strangers asking for bank information, gift cards, cryptocurrency payments, or fake-check transactions.
You can check the FTC’s job scam advice before accepting an unfamiliar offer.
Getting to $1,000 a few weeks later is better than losing your savings to a scam.
Cut Spending Without Giving Up Everything You Enjoy
You don’t have to stop having fun just because you’re trying to save money.
But small purchases can add up surprisingly fast.
A drink here, a game purchase there, and a few snacks during the week might take more of your money than you realize.
The solution isn’t to cut out everything.
It’s to decide what matters most.
Track Your Spending for Seven Days
For one week, write down every optional purchase you make.
Don’t change your spending at first. Just track it.
You might notice something like this:
| Weekly Purchase | Money Spent |
|---|---|
| Three drinks at $4 each | $12 |
| Game purchase | $10 |
| Extra snacks | $8 |
| Total | $30 |
That’s $30 in one week.
Over four weeks, those purchases would total $120.
You don’t have to stop buying all of them.
Maybe you decide to save $15 each week by skipping a few purchases you don’t care much about.
That’s another $60 toward your savings goal in four weeks.
Only count money as savings if you really would have spent it otherwise. And never skip meals, school essentials, or necessary expenses to meet a savings target.
Try a 24-Hour Pause Before Buying Something
Here’s a simple trick for impulse spending.
When you want something that isn’t necessary, wait 24 hours before buying it.
Ask yourself:
“Do I still want this, or do I want to reach my $1,000 goal faster?”
Sometimes you’ll still want the item.
Other times, you’ll realize you were just bored or excited about seeing something new.
You can also try a short no-spend challenge for optional purchases. Start with one or two days rather than making rules you’ll struggle to follow.
The goal is to make better choices, not punish yourself.
Move Your Savings Before Spending the Rest
One of the easiest money-saving habits is called pay yourself first.
That means moving some money into savings as soon as you receive it.
Let’s say you get $50.
Instead of spending money and saving whatever remains, you immediately set aside $30.
Now you have $20 available for spending.
You’ve already made progress toward your goal.
If your bank allows automatic savings transfers, you can use them to make this easier.
You can also set a reminder for every payday or allowance day.
Build a 30-, 60-, or 90-Day Plan to Reach $1,000
Now you know how to earn more, spend less, and calculate your target.
It’s time to put everything together.
Below are three example plans.
They aren’t promises that every teenager can earn these amounts. They’re models you can adjust based on your actual income, age, expenses, and available time.
The 30-Day Plan: When You Can Save Aggressively
This plan works best if you already have money saved, items you can legally sell, or a reliable income source.
Here’s one possible breakdown:
| Savings Source | Amount |
|---|---|
| Selling unused belongings | $200 |
| Saving $150 per week from take-home earnings for 4 weeks | $600 |
| Cutting $50 per week of optional spending for 4 weeks | $200 |
| Total Saved | $1,000 |
This example reaches $1,000 in four weeks, or 28 days.
But look closely at what it requires.
You would need $600 available from earnings, $200 worth of belongings to sell, and $200 in spending you could actually cut.
Many teenagers won’t have all three.
If you don’t, there’s no reason to force this plan.
Choose a longer deadline rather than trying unsafe jobs or borrowing money.
The 60-Day Plan: A More Flexible Approach
An eight-week plan gives you more time to build your savings.
Suppose you’re able to save the following each week:
| Weekly Savings Source | Amount |
|---|---|
| Take-home earnings from permitted work | $85 |
| Allowance saved | $20 |
| Reduced optional spending | $20 |
| Weekly Total | $125 |
After eight weeks:
$125 × 8 = $1,000
This plan reaches the target in 56 days, leaving a few extra days within a 60-day deadline.
You could make it easier by adding money you already have or extending the deadline.
For example, starting with $200 means you only need $800 more.
Over eight weeks, that’s $100 per week instead of $125.
The 90-Day Plan: For Teens With Limited Income
A three-month saving goal gives you more room to handle school, homework, and changing schedules.
Here’s an example using a 12-week saving period, which fits within 90 days:
| Savings Source | Amount |
|---|---|
| Existing savings or one-time extra money | $100 |
| $40 weekly take-home earnings × 12 weeks | $480 |
| $25 weekly allowance saved × 12 weeks | $300 |
| $10 weekly spending reduction × 12 weeks | $120 |
| Total | $1,000 |
This plan reaches $1,000 in 84 days.
Notice that no single source provides all the money.
You’re combining several smaller contributions.
But if you don’t receive an allowance or can’t earn $40 per week, the numbers will need to change.
For example, saving $40 every week for 25 weeks also gets you to $1,000.
That’s roughly six months.
The important thing is to choose a plan you can keep following.
Track Your Progress Every Week
Whatever timeline you choose, check your progress once a week.
A simple tracker could look like this for an eight-week plan:
| Week | Total Savings Target |
|---|---|
| 1 | $125 |
| 2 | $250 |
| 3 | $375 |
| 4 | $500 |
| 5 | $625 |
| 6 | $750 |
| 7 | $875 |
| 8 | $1,000 |
You can record your actual balance next to each target.
Use a notebook, a spreadsheet, or a savings tracker.
Seeing your progress can help you stay motivated. It also tells you early when your plan needs an adjustment.
Where Should a Teenager Keep the $1,000?
Imagine saving $400, keeping it in your everyday spending money, and accidentally using half of it.
That can happen when all your money is mixed together.
Keeping your savings separate makes the goal easier to manage.
Open a Teen Savings Account With Adult Help
Many banks and credit unions in the United States offer accounts designed for teenagers.
If you’re under 18, you will often need a parent or legal guardian to help open an account. The exact requirements depend on the institution and state.
Look for an account with:
- No monthly maintenance fee, if possible
- Low or no minimum balance requirement
- Convenient deposits
- Online balance tracking
- Clear withdrawal rules
- Federal deposit insurance
At an FDIC-insured bank, eligible deposits are protected up to the applicable insurance limits, generally $250,000 per depositor, per insured bank, per ownership category.
The National Credit Union Administration (NCUA) provides similar federal share insurance at federally insured credit unions.
A $1,000 savings goal is well below those standard limits, but you should still check that the institution is insured.
You can find more information through FDIC GetBanked and the NCUA.
Keep Goal Money Separate From Everyday Spending
A checking account is usually more convenient for everyday purchases.
A savings account is generally a better place for money you’re trying not to touch.
Some teenagers may also have access to a high-yield savings account (HYSA), which can offer a higher interest rate.
When comparing accounts, look at the Annual Percentage Yield (APY). It shows how much interest you could earn over a year with compounding, assuming the rate remains the same and the account meets its terms.
However, don’t expect interest to do most of the work for a short-term $1,000 goal.
Your regular deposits will matter far more.
If you have direct deposit from a job, ask your bank whether part of your paycheck can go straight into savings.
The less often you see that money available for everyday purchases, the easier it may be to leave it alone.
What If You’re Falling Behind Your Savings Goal?
You made your plan.
You followed it for a few weeks.
Then something happened.
Maybe you didn’t get as many work hours as expected, had a necessary expense, or simply couldn’t save enough.
That doesn’t mean the plan is over.
It means you need to update it.
Calculate How Much You Still Need
Suppose your goal was to save $1,000 over 12 weeks.
After four weeks, you’ve saved $240 instead of roughly $333.
You still need:
$1,000 − $240 = $760
And you have eight weeks left.
$760 ÷ 8 = $95 per week
Your new target is $95 weekly.
Now you can decide whether that amount is realistic.
Adjust Your Plan Instead of Giving Up
If saving $95 per week isn’t possible, consider extending your deadline.
For example, if you give yourself 11 more weeks to save the remaining $760, your new target is about $69.10 weekly.
That’s a noticeable difference.
You might also look for a permitted weekend job, save a larger share of a future paycheck, or reduce a few optional purchases.
But don’t count money you haven’t earned yet.
And don’t spend your emergency savings, borrow money, or take risky financial shortcuts just to make your progress tracker look better.
Saving money is supposed to improve your financial situation.
BMI & BMR CALCULATOR - CHECK YOUR HEALTH
Frequently Asked Questions
Can I Save $1,000 if I Only Get $5 or $10 a Week?
Yes, but it will take longer unless you find another source of money.
Starting from zero, saving $5 every week would take 200 weeks to reach $1,000.
Saving $10 every week would take 100 weeks.
If you want to reach your goal sooner, you can look for age-appropriate earning opportunities, save occasional gifts, or reduce optional spending where possible.
Can My Parents Help Me Reach My Savings Goal?
Yes, if they’re willing and able to help.
For example, you could ask whether they would consider matching part of what you save.
If you save $20 and your parents agree to add $10, your savings grow by $30.
You could also ask about extra paid tasks beyond your regular household responsibilities.
However, family contributions should never be assumed. Build your plan around what has actually been agreed upon.
Should I Invest the First $1,000 I Save?
That depends on when you’ll need the money.
If you’re planning to use the $1,000 in a few months, keeping it in an insured savings account may be more suitable than investing it in the stock market.
Investments can lose value, especially over short periods.
If you’re saving for a long-term goal, investing may be worth learning about with a parent or trusted financial professional.
But don’t confuse investing with saving money for something you need soon.
What Should I Do After Saving My First $1,000?
First, decide what the money is for.
Maybe you’re saving for a laptop, your first car, college expenses, or an emergency fund.
If your goal is an emergency fund, keep the money accessible in a safe savings account.
If you’ve reached a purchase goal, take time to compare prices and make sure you’re ready to spend.
You can also choose a new target, such as $1,500 or $2,000.
The biggest benefit of saving your first $1,000 isn’t just the money.
It’s learning how to set a financial goal and follow through.
Your First $1,000 Starts With a Weekly Plan
You don’t need to become a money expert to save your first $1,000 as a teenager.
Start with what you already have. Work out how much you can save each week, look for safe and legal ways to earn extra money, and stop spending on things that matter less than your goal.
If a 30-day savings challenge doesn’t fit your life, choose 60 days, 90 days, or a longer timeline.
Small amounts still count, and steady progress is better than a plan you can’t maintain.
Your first step today is simple: check how much money you already have, choose a realistic deadline, and calculate your weekly savings target.
That’s where your first $1,000 begins.